Skip to content
For everyday spending, use a checking account. For emergency cash or short-term savings, use a high-yield savings or money market account. For investing or leveraged trading, choose a trading account sized to your capital and risk tolerance. Each of these does one job well and does the others poorly, which is exactly why the comparison confuses people. Checking accounts win on liquidity but pay almost nothing. Certificates of deposit offer better rates in exchange for locking your money away, and trading accounts offer the highest potential return alongside the highest risk of loss.
Start here:
- Identify your primary job: spend, save, or trade.
- Match that job to the account class below, not the other way around.
- Scan the comparison table further down before opening anything.
Key Takeaways
The right account choice depends on matching liquidity, yield, and risk to a single clearly defined purpose rather than picking whichever account sounds the most familiar.
| Point | Details |
|---|---|
| Match account to purpose | Checking for spending, savings/MMA for short-term goals, CDs for locked-in rates, trading accounts for market exposure. |
| Liquidity and yield trade off | Checking offers the highest access with the lowest return; CDs offer the opposite. |
| Demo accounts test features, not outcomes | Live slippage and trading psychology differ from simulated performance, especially in volatile markets. |
| Combine accounts strategically | Pairing checking with high-yield savings, or laddering CDs, balances access against return. |
| Cubomarkets fits active traders | Spreads from 0.0 pips, zero commission, and over 3 million executed orders support cost-conscious, execution-sensitive trading accounts. |
Table of Contents
- Bank Account Types Compared: Checking, Savings, MMA, and CDs
- Trading and Brokerage Account Types Explained
- Which Account Type Fits Your Goal?
- How to Compare Accounts: A Practical Checklist
- How Execution Quality Affects Your Trading Account Choice
- What Most Account Comparisons Get Wrong
- Open the Trading Account That Matches Your Strategy
- Frequently Asked Questions
- Sources
Bank Account Types Compared: Checking, Savings, MMA, and CDs
Deposit accounts split into four core types, and each one trades liquidity for yield in a different way. Checking accounts sit at the top of the liquidity scale because you can move money out instantly through debit cards, checks, or transfers, but that convenience comes at a cost: interest rates are usually close to zero.
Savings accounts strike a middle ground. You still have reasonably fast access to funds, often limited to a handful of withdrawals per statement cycle, and you earn a modest return. Money market accounts (MMAs) push that a step further. They typically require higher minimum balances but reward you with better rates and limited check-writing privileges, functioning as a hybrid between a checking and savings account.
Certificates of deposit, or term deposits, sit at the opposite end from checking. You lock your money in for a set period, anywhere from a few months to several years, in exchange for a fixed rate that’s usually higher than a standard savings account. Withdraw early and you’ll pay a penalty that often eats into the interest earned.
- Checking/current account: highest liquidity, near-zero yield, minimal or no minimum balance.
- Savings account: moderate liquidity, modest yield, low minimums, some withdrawal caps.
- Money market account: moderate to high minimums, better yield than savings, limited transactional access.
- CD/term deposit: lowest liquidity, highest fixed yield, penalty for early withdrawal.
Here’s the gap that catches people off guard: the difference between a checking account’s near-zero yield and what high-yield online savings and money market accounts have historically advertised can be significant, though exact rates shift constantly with market conditions. That spread is the whole reason financial planners tell you to stop leaving idle cash in checking.
Student, custodial, and retirement accounts follow the same liquidity logic but add rules around who owns the funds, when they can be withdrawn, and what tax treatment applies. Treat them as variants of the four core types rather than a separate category to learn from scratch.
Trading and Brokerage Account Types Explained
Forex and CFD brokers generally offer four practical account tiers, and the differences come down to lot size, minimum capital, and how much control you keep over your own trades. Standard, mini, micro, and managed accounts each serve a distinct trader profile, and picking the wrong one is a common reason new traders either overextend their risk or get bored with position sizes too small to matter.
- Standard accounts trade in full lots (100,000 units) and suit traders with enough capital to absorb normal price swings without excessive leverage.
- Mini accounts trade 10,000-unit lots, cutting capital requirements and risk per trade to roughly a tenth of standard.
- Micro or cent accounts go smaller still, often 1,000-unit lots, letting beginners practice real execution with real money at minimal stakes.
- Managed accounts hand trade decisions to a professional in exchange for a fee, which means less day-to-day control but no need to watch charts yourself.
- Swap-free (Islamic) accounts remove overnight interest charges on positions held past the daily rollover, structured to comply with religious finance principles rather than to boost returns.
Demo accounts deserve a specific warning. They’re genuinely useful for learning a platform’s order types and charting tools before risking a dollar. But demo performance doesn’t reliably reproduce slippage or the psychological pressure of trading with real money, especially during volatile news events when fills on a live account can differ sharply from what a simulator shows you.
Pro Tip: Spend two weeks on a micro or cent account with real (small) money before scaling up. It’s the closest thing to a demo that still forces you to feel the trade.
Mini and micro accounts are particularly effective for learning position sizing because the dollar amounts at risk stay small enough that a bad week teaches a lesson instead of wiping out a month’s savings.
Which Account Type Fits Your Goal?
Matching an account to a goal gets easier once you stop comparing checking accounts to trading accounts as if they compete for the same job. They don’t. The table below groups categories by what they’re actually for.
| Category | Best for | Liquidity | Typical yield/return | Fees | Minimum deposit | Risk profile |
|---|---|---|---|---|---|---|
| Everyday transaction account | Daily spending and bill pay | Very high | Minimal to none | Usually low or waived with balance | Often none | Very low |
| High-yield savings / MMA | Emergency fund, short-term goals | High to moderate | Modest, above standard savings | Low, occasional balance requirements | Low to moderate | Very low |
| Term deposit / CD | Locking in a rate on funds you won’t need soon | Low (penalty on early access) | Fixed, generally higher than savings | Early withdrawal penalty | Moderate | Very low |
| Standard trading account | Traders with sufficient capital and experience | High (subject to market hours) | Variable, market-driven, can be negative | Spread/commission, possible swap fees | Moderate to high | High |
| Mini/micro trading account | Beginners learning position sizing | High (subject to market hours) | Variable, market-driven, can be negative | Spread/commission, possible swap fees | Low | Moderate to high |
| Managed trading account | Hands-off investors wanting professional execution | Moderate (subject to lock-in terms) | Variable, depends on manager performance | Management/performance fee plus trading costs | Higher | High |
A few combinations come up again and again in practical planning:
- Pair a checking account for cash flow with a high-yield savings account for your emergency fund. This two-account setup is a common recommendation because it keeps spending money liquid while idle savings actually earn something.
- If you’re staggering larger sums, a CD ladder lets portions of your money mature on a rolling schedule so you’re never locked out of all your cash at once.
- Before funding a live trading account, run the platform’s demo mode first, but treat it as a features test, not a performance forecast.
How to Compare Accounts: A Practical Checklist
Choosing between account types gets simpler when you work through the same short list every time, whether you’re opening a savings account or a trading account.
- Define the job first. Are you storing cash you’ll need next month, building a rate-locked nest egg, or putting risk capital to work in the market? The answer eliminates most options immediately.
- Confirm liquidity and limits. Ask how many withdrawals you get per cycle, whether there’s a lockup or penalty, and how fast funds actually clear once you request them.
- Compare the full fee schedule. Monthly maintenance, minimum balance fees, wire fees, and for trading accounts, spreads, commissions, and overnight swap charges all add up differently depending on how you trade.
- Check protection and regulation. Deposit insurance frameworks vary by country, so verify what actually covers your funds before you wire anything to a new provider.
- Test before you commit capital. Use a demo account to learn the interface, then start with a small live position to see how real execution behaves.
Exact questions worth asking a bank or broker directly: How long do deposits and withdrawals actually take, and what fees apply to each? What’s the margin or leverage limit, and is negative balance protection included? What’s the account opening and verification (KYC/AML) process, and how long does it take?
Pro Tip: Ask for the fee schedule in writing before you fund anything. A broker or bank that hesitates to give you a clear, itemized answer is telling you something.
Red flags worth walking away from: a license number that can’t be verified with the regulator it claims, a fee schedule that’s vague or scattered across support articles instead of one clear page, no demo or test environment for a trading platform, and any pattern of delayed withdrawals reported by existing account holders.
How Execution Quality Affects Your Trading Account Choice
Account type only tells half the story on the trading side. The other half is what happens after you place an order, and that’s where platform execution quality separates a good trading account from a frustrating one. Cubomarkets processes spreads starting at 0.0 pips with zero commission and has executed more than 3 million orders, numbers that matter because slow fills and wide spreads quietly erode returns no account-type comparison chart will show you.
Low spreads and fast execution don’t fix a bad strategy, but they stop a good one from bleeding out through slippage and delayed fills, the two costs that never show up in the marketing copy for any account tier.
A platform’s Customer Due Diligence policy matters just as much during account opening. A clear, documented KYC process reduces onboarding friction and signals the broker is actually verifying who’s on the platform, which cuts fraud risk for everyone using it. Real-time analytics and transparent execution reporting let you check whether your fills match what the account type promised on paper.
What Most Account Comparisons Get Wrong
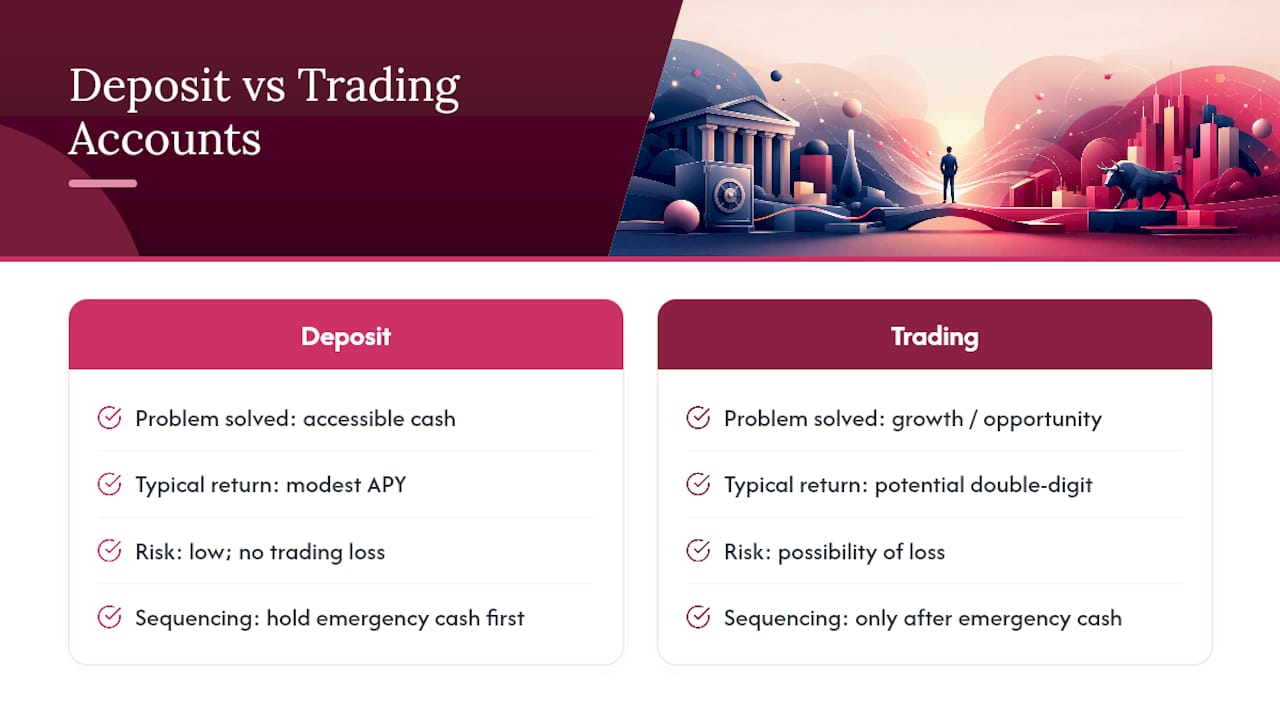
Most guides treat this as a single decision: which account is “best.” It isn’t. Deposit accounts and trading accounts solve different problems, and comparing their yields side by side, the way plenty of generic charts do, misleads more than it clarifies. A savings account paying a modest APY isn’t “worse” than a trading account with double-digit potential returns. It’s a different tool solving a different job, and the trading side carries the possibility of loss that a savings account simply doesn’t.
The conventional advice to “just open a high-yield savings account and a brokerage account” skips the sequencing that actually matters. Liquidity needs come first. Emergency cash has to be sitting somewhere accessible before a single dollar goes toward leveraged trading, because the traders who get into trouble are usually the ones who funded a trading account with money they needed back in three weeks.
If there’s one thing worth prioritizing above account type entirely, it’s execution quality on whichever trading account you eventually open. Spread, fill speed, and withdrawal reliability affect your real return more than the label on the account tier.
Open the Trading Account That Matches Your Strategy
Cubomarkets gives you the execution side of this comparison without the trade-offs that usually come with it: spreads starting at 0.0 pips, zero commission, and fast order execution across Forex, indices, commodities, stocks, and crypto CFDs, all backed by more than 3 million orders processed on the platform.
Whether you’re moving up from a micro account or testing strategy on demo first, Cubomarkets supports flexible trading account types built for both new and experienced traders, with instant deposits and withdrawals so your capital isn’t stuck waiting on the platform. Practice on MetaTrader 5 with real-time analytics, then scale into a live account once you’re comfortable with how the platform actually fills your orders. Open a Cubomarkets account today and pick the account type that matches where you are right now, not where a generic comparison chart assumes you should be.
Frequently Asked Questions
What’s the main difference between a bank account and a trading account?
A bank account stores and protects your cash while paying limited interest. A trading account lets you buy and sell financial instruments like Forex, stocks, or commodities, with the potential for higher returns and the real possibility of losing money.
Which account type is best for a beginner?
For cash management, a checking account paired with a high-yield savings account covers most needs. For trading, mini or micro accounts let you learn position sizing with smaller capital at risk before moving to standard lots.
Are demo trading accounts a reliable predictor of live performance?
Not fully. Demo accounts are useful for learning platform features, but they typically don’t reproduce the slippage or emotional pressure that comes with trading real money.
Is my money protected in a deposit account?
Deposit insurance coverage varies by country and provider, so confirm the specific protection that applies to your account before you fund it.
Can I hold both a bank account and a trading account at the same time?
Yes, and most people should. A checking or savings account handles daily spending and emergency funds, while a separate trading account handles risk capital you’re prepared to invest in the market.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Compare savings, checking, CDs, and money market accounts | Citi
- Forex Basics: Setting Up an Account | Investopedia
- Types of bank accounts: Basics | MoneyLion